How Corresponding Adjustments Prevent Double Taxation in Transfer Pricing Cases
September 10, 2026
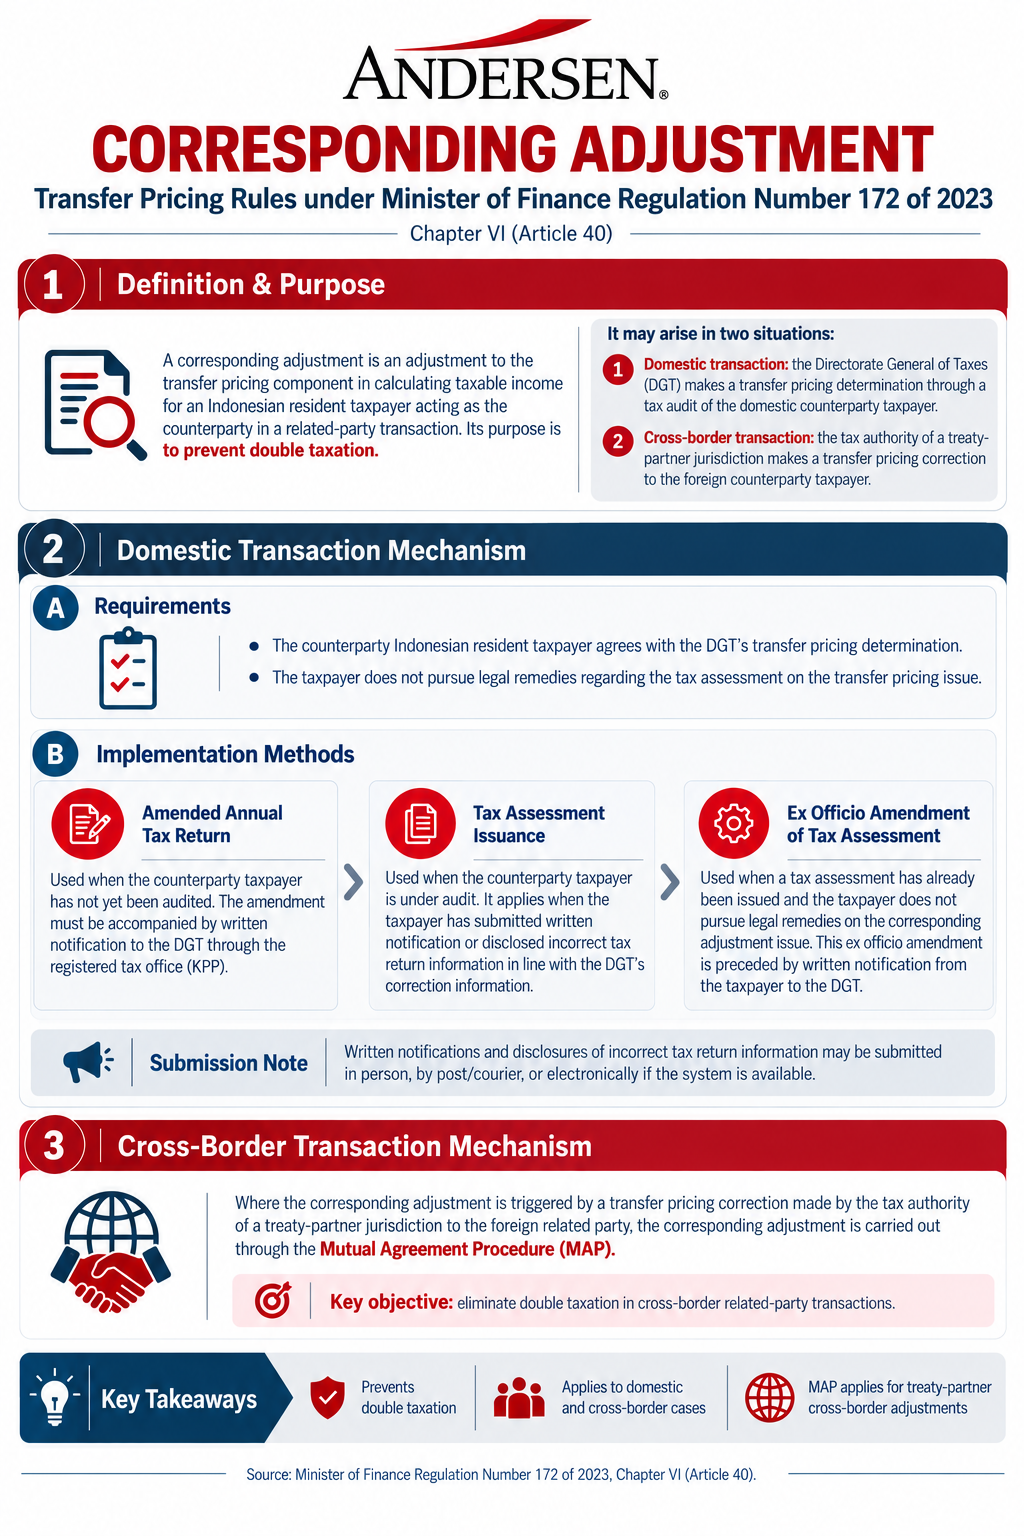
A corresponding adjustment allows an Indonesian resident taxpayer to adjust the transfer pricing component of their taxable income when a related-party transaction has already been corrected elsewhere, whether by the Directorate General of Taxes in a domestic case or by a treaty-partner tax authority in a cross-border case, in order to prevent double taxation. Under Article 40 Minister of Finance Regulation (“PMK”) No 172 of 2023, this adjustment can be carried out through an amended tax return, a tax assessment, or an ex officio amendment for domestic transactions, while cross-border cases are resolved through the Mutual Agreement Procedure (MAP). The infographic below outlines the requirements and mechanisms for both situations.
Recent News
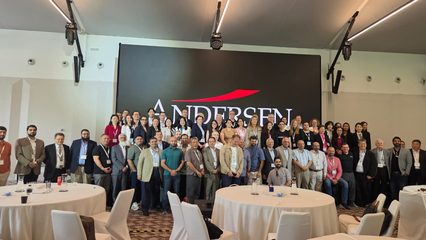
Asia Pacific – Middle East Regional Partner Meeting
Read More »
The Challenges of Responding to SP2DK and Tax Audits: A Session with Aspelindo Members
Read More »