The Procedure for MAP Requests Lodged by the DGT under PMK 172/2023 Explained
October 1, 2026
Under Minister of Finance Regulation No. 172 of 2023 (“PMK 172/2023”) (Article 41, paragraph 3(c)), in addition to taxpayers and Indonesian citizens, the Director General of Taxes (“DGT”) has the right to request implementation of the Mutual Agreement Procedure (“MAP”) set out in the country’s double taxation agreements (“DTAs”).
Grounds for the DGT to request MAP implementation
The DGT can request MAP implementation for the following two reasons:
- To follow up on a domestic taxpayer’s MAP implementation request.
- To follow up on a taxpayer’s application for a bilateral and multilateral transfer price agreement submitted in accordance with the procedures for implementation of the transfer price agreement.
Requirements for the DGT’s MAP implementation request
Based on Article 42, paragraph 2, the DGT’s request to follow up on a domestic taxpayer’s MAP implementation request must meet all of the following conditions:
- Be written in Indonesian.
- Describe the DGT’s tax treatment that is considered not in accordance with the DTA.
- Be submitted within the time limit stipulated in the DTA or no later than three years since the treatment occurred.
- Be signed by the domestic taxpayer or its representative in accordance with Article 32, paragraph 1 of the Law on General Provisions and Tax Procedures (KUP Law).
- Have evidence attached showing that the tax treatment by the DGT is not in accordance with the provisions of the DTA.
Provisions for submitting MAP implementation requests
The request for MAP implementation to follow up on a domestic taxpayer’s MAP implementation request is submitted to the Directorate of International Taxation, not the KPP where the taxpayer is registered. The request can be sent directly via post/courier or electronically.
Other conditions
Domestic taxpayers can submit requests for legal remedies simultaneously with the request for MAP implementation. Per Article 41, paragraph 3 (a), (c), and (d), these include:
- Initiating a lawsuit in accordance with Article 23 of the KUP Law.
- Lodging an objection in accordance with Article 25 of the KUP Law.
- Appealing in accordance with Article 27 of the KUP Law.
- Applying for the reduction or cancellation of an incorrect tax determination letter in accordance with Article 36, paragraph 1(b) of the KUP Law.
- Applying for a review in accordance with Article 77, paragraph 3 of the Law on Tax Courts.
With this mechanism, the MAP proposed by the DGT basically still starts from the taxpayer’s initiative through the proposed channel, not the unilateral action of the DGT. This mechanism also provides domestic taxpayers with an additional avenue to challenge the interpretation or correction of the DGT’s own transfer price, aside from lodging unilateral objections or appeals domestically.
The Andersen in Indonesia team can assist in drafting a proposed MAP request that meets the requirements of Article 42, paragraph 2, including preparing supporting evidence and monitoring the research deadline by the DGT. Contact our team for a consultation before the deadline for submitting your MAP proposal expires.\
By Olina Rizki Arizal – Senior Partner
Recent News
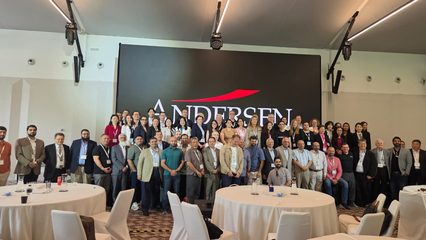
Asia Pacific – Middle East Regional Partner Meeting
Read More »
The Challenges of Responding to SP2DK and Tax Audits: A Session with Aspelindo Members
Read More »